Riding the Income Rollercoaster Without a Safety Harness
I remember staring at my bank app at 2 AM, feeling a heavy weight right in the middle of my chest. My freelance income had completely dried up for three solid weeks. I had rent due, groceries to buy, and absolutely no safety net to catch me.
Every single notification on my phone made my stomach drop, because I thought it was another bill I could not pay. I felt totally trapped in a vicious cycle of making great money one month and panicking the next. That terrifying, sleepless night forced me to rethink everything I ever knew about saving money.
Living with an unpredictable paycheck feels exactly like walking a tightrope without a harness. You probably know exactly what I am talking about. One month you are celebrating a huge project payout, feeling like you have finally figured life out.
The next month, client work randomly vanishes or your shifts get unexpectedly cut. Suddenly, you are frantically scrambling just to cover your basic utilities. This constant up-and-down motion creates a deep, lingering anxiety that completely ruins your peace of mind.
You start second-guessing every single tiny purchase you make at the grocery store. A simple dinner out with friends feels like a massive financial crime. You feel guilty because you have absolutely no idea when your next paycheck will arrive.
Instead of enjoying the amazing freedom of being your own boss, you end up feeling like a hostage to your incoming bills. Sleep quickly becomes a rare luxury. Your relationships begin to suffer because you are always secretly stressed about money.
It is a lonely, exhausting way to live your life. The constant fear of an unexpected medical bill or a broken car engine hovers over your head like a dark, heavy cloud. Traditional personal finance advice always assumes you have a steady, predictable salary dropping into your account every two weeks.
But for those of us living the gig economy, freelance, or commission-based life, that cookie-cutter advice is practically useless. We need a completely different approach to protect our mental health and our wallets.
Decoding the Feast and Famine Money Cycle
If you want to stop feeling anxious about money, you have to understand the core problem first. The biggest trap people with fluctuating incomes fall into is adjusting their lifestyle based on their current month. When a massive check clears, human psychology tricks us into feeling incredibly rich.
We immediately upgrade our dinners, buy that new gadget we have been eyeing, or book a weekend trip. We subconsciously assume that this high income level is our new normal. But logic tells us that a slow season is always waiting just around the corner.
When that slow season hits, we are suddenly stuck with expensive habits and zero cash reserves. This is exactly why you need a specialized system that acts as a shock absorber for your finances. A regular budget simply tracks where your money goes.
A variable income framework actively smooths out the massive bumps in your cash flow. It takes the emotional highs and lows out of your banking experience.
Myth vs Reality: The Savings Trap
The Common Myth: You should try to save a strict 20% of your income every single month.
The Hard Reality: Saving a fixed percentage fails completely when your income drops below your basic living costs.
Forcing yourself to save 20% during a terrible month will just put you into credit card debt. You have to adapt your savings rate dynamically based on what actually hits your bank account.
Step 1: Discovering Your Absolute Bare-Bones Baseline
Before you can build a massive safety net, you need to know exactly how much ground you are trying to cover. Standard budgeting tells you to list out every single expense you have. We are going to ignore that advice entirely.
Instead, we need to calculate your absolute "survival number". This is the exact amount of money you need to keep a roof over your head and food in your stomach. It does not include streaming services, new clothes, or eating at restaurants.
You need to know this exact number so that you know the bare minimum you have to earn to survive. Let us look at a practical way to separate your survival needs from your thriving needs.
Once you calculate the left column, write that exact number down on a sticky note. Put that note on your bathroom mirror or your computer monitor. That specific number is your primary target during any low-income month.
Any money you make above that survival number is where your real financial power begins. It is the excess cash that will eventually build your impenetrable safety net.
Automating the Baseline Mentality
The biggest secret to managing fluctuating cash is to pretend you always make exactly your survival number. Even when you land a massive ten-thousand-dollar contract, you should live as if you only made your bare minimum.
This requires a massive mental shift. You have to stop viewing your business account balance as your personal spending money. The money in your main account belongs to your future self, not your current self.
Step 2: The Two-Account Strategy for Emotional Distance
Mixing your business revenue with your personal grocery money is a recipe for total disaster. When all your cash sits in one single checking account, your brain gets easily confused. You look at a large balance and think you can afford a new television.
To fix this, you need to create intense physical and emotional distance from your money. You should set up a completely separate "Holding Account" at a different bank. Make sure this new bank does not give you a debit card for easy access.
Whenever you get paid by a client or an employer, 100% of that money goes directly into the Holding Account. Do not keep a single penny in your main checking account yet. This Holding Account acts as a giant dam, holding back the flood of money.
Then, on the first day of every month, you manually transfer only your "survival number" to your regular checking account.
Pro Tip: I used to keep all my freelance earnings in my primary checking account, and I would constantly overspend on takeout food just because the balance looked high. The day I moved my holding account to a completely different bank where transfers took three days to clear, my random impulse buying completely stopped. Physical friction is the best cure for bad spending habits.
This simple two-account strategy changes everything about how you view money. During a "feast" month, your Holding Account will grow massively. During a "famine" month, your Holding Account will slowly shrink, but your personal checking account will stay exactly the same.
Your day-to-day life remains completely stable regardless of how many clients you booked. This is how you finally stop the emotional roller coaster of a variable paycheck.
Handling the Overflow
So, what do you do with all the extra cash building up in the Holding Account? This is where your actual emergency fund comes into play.
Here is a powerful strategy to watch before moving forward:
If you want a visual breakdown of how to route your money perfectly, this video explains the "bucket strategy" better than anything else I have seen.
Once your Holding Account has enough cash to cover at least one full month of your survival number, the magic happens. Every single dollar you earn above that buffer goes straight into a high-yield savings account.
This high-yield account becomes your official emergency fund. You are essentially building a financial fortress, brick by brick.
Step 3: The Percentage-Based Allocation Trick
Sometimes, calculating a strict survival number feels too restrictive for highly creative people. If you hate tracking every single penny, you can use the percentage method instead.
With this method, you decide on specific percentages for your money before the check ever arrives. For example, you might decide that 50% goes to daily living, 30% goes to taxes, and 20% goes to your emergency fund.
When a tiny $500 check arrives, you still follow the exact same rule. You send $100 strictly to your savings without overthinking it. When a massive $5,000 check clears, you happily send $1,000 to your savings.
This method scales perfectly with your income fluctuations. It completely removes the stressful decision-making process from saving money. You never have to ask yourself if you can afford to save this month.
The math simply makes the decision for you. It protects you from yourself during those euphoric moments when a big payment clears.
Step 4: Re framing What an Emergency Actually Means
One of the biggest reasons variable income earners fail at saving is because they keep dipping into their funds. They build up a decent safety net, and then immediately drain it for a "business expense".
You need to establish aggressively strict rules for what qualifies as a true emergency. A new laptop because your old one is a little slow is not an emergency. A sudden medical bill that threatens your health is an absolute emergency.
A client paying you three weeks late is an inconvenience, not a reason to drain your savings. You should rely on your Holding Account buffer for late client payments. Your true emergency fund should only be touched when absolute disaster strikes.
The Three-Question Test
Before you transfer a single dollar out of your emergency savings, ask yourself three simple questions.
- Is this expense completely unexpected?
- Is this expense absolutely necessary for my immediate survival?
- Will ignoring this expense cause me physical or intense financial harm?
If the answer to all three questions is not a loud and clear "yes", then leave your savings alone. You will have to find another way to cash flow that specific problem.
This harsh mental discipline is exactly what separates successful gig workers from those who are constantly broke. It forces you to get incredibly resourceful with the money you already have available.
Step 5: Preparing for the Silent Wealth Killers
When you work for a traditional company, they magically handle your taxes and health insurance behind the scenes. When your income fluctuates, these invisible expenses become your biggest threat.
Many freelancers completely forget about taxes until April rolls around, and then they panic. They end up draining their hard-earned emergency fund just to pay the government. This resets all their amazing financial progress back to zero.
To prevent this tragedy, you must treat your taxes like a monthly utility bill. Every time you get paid, immediately slash off 25% to 30% and hide it in a dedicated tax folder. Never mix your tax money with your emergency money.
If you mentally combine the two, you will falsely believe you have a massive safety net. Then, tax season will arrive and destroy your sense of security entirely.
Planning for the Known Unknowns
You also need to plan for annual expenses that you know are coming but often forget about. Things like car registration, website hosting fees, or professional licenses.
These are not true emergencies because you know they happen every single year. Yet, they constantly catch gig workers completely off guard.
You should divide the total annual cost of these items by twelve. Then, treat that tiny fraction as part of your monthly baseline survival number. This completely smooths out the financial bumps throughout the calendar year.
By actively predicting these annoying expenses, you protect your emergency fund from taking unnecessary hits. You start operating like a real, structured business instead of a struggling freelancer.
Building a robust safety net on an unpredictable paycheck is not about sheer willpower. It is purely about building a mechanical system that protects you from your own human nature.
Every single dollar you save buys you a small piece of your future freedom. It buys you the amazing ability to sleep deeply through the entire night. It gives you the power to say no to terrible clients who do not respect your valuable time.
You do not have to have everything perfectly figured out today. You just have to start making small, intentional choices with the very next check that hits your account.
If you can master these fundamental behaviors, your income fluctuations will stop feeling like a terrifying rollercoaster. They will simply become normal bumps on your road to total financial independence. Keep pushing forward and trust the mathematical process.
Next-Level Strategies for Unpredictable Paychecks
Once you have established your basic survival number, it is time to shift from defense to offense. Managing an irregular income requires you to completely outsmart your own spending habits. You need advanced tactics that work exactly the way your brain works.
The biggest challenge with saving money on a variable income is maintaining your momentum. When a massive contract finally pays out, your first instinct is to reward yourself. We need to redirect that natural human instinct into something that builds long-term wealth.
One of the most effective ways to do this is by ignoring massive financial goals entirely. Looking at a huge savings target can actually cause more anxiety than it relieves. Let us explore how you can trick your brain into saving more money without feeling deprived.
The Magic of Tiered Milestone Tracking
Traditional finance gurus tell you to save six months of living expenses immediately. If your survival number is four thousand dollars, saving twenty-four thousand feels impossible when your income bounces around. This giant number causes immediate decision fatigue.
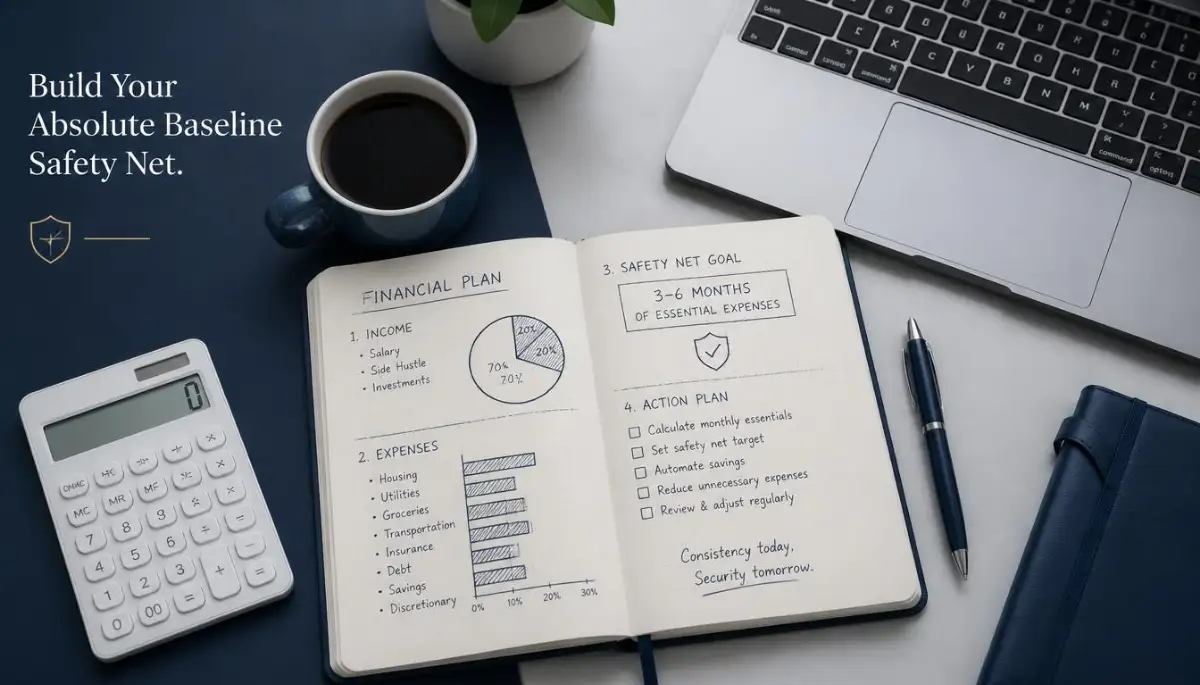
Instead of chasing one massive number, you should break your safety net into three distinct tiers. Tier one is your 30-day buffer. This is just enough money to cover one single month of bare-minimum expenses.
When you hit tier one, you should genuinely celebrate that win. Tier two is your 90-day peace of mind fund. Reaching this level means you could theoretically lose all your clients tomorrow and still survive for three months.
Tier three is your ultimate six-month fortress. By breaking the goal into these smaller, bite-sized pieces, you trigger a sense of constant achievement. According to research on financial stress from the American Psychological Association, celebrating small money milestones actively reduces daily anxiety.
Creating Artificial Income Stability
You do not have to just sit around and wait for clients to pay you on their own timeline. You can actively design your business to provide smoother cash flow. This is a game-changer for anyone who wants to protect their savings buffer.
Whenever you sign a new client, never agree to a single lump-sum payment at the very end of the project. Instead, demand a fifty percent upfront deposit before you even start working. You can then split the remaining balance into smaller weekly milestones.
This simple billing adjustment completely eliminates those terrifying zero-dollar weeks. The Consumer Financial Protection Bureau offers great advice on managing irregular cash flow, and their biggest tip is smoothing out your incoming deposits.
If you want to truly stabilize your earnings, you should also focus on creating assets that sell themselves. Spending time building products that people actually love can provide a steady trickle of passive income. Even an extra few hundred dollars a month can completely cover your utility bills during a slow season.
The Micro-Transfer Habit
Sometimes, manually transferring huge chunks of money to your savings account physically hurts. We experience a psychological loss when we see our checking account balance drop significantly. You can easily bypass this mental block by using the micro-transfer method.
Set up an automated rule in your banking app to transfer just five dollars every single day into your high-yield savings. Five dollars is such a tiny amount that you will never even notice it missing from your daily budget.
By the end of the month, you have effortlessly saved one hundred and fifty dollars. This happens completely in the background while you focus on running your business.
Make sure this money is sitting in a properly insured account so it remains completely protected. You can always check the FDIC guidelines on insured deposit accounts to ensure your money is safe from bank failures.
The Hidden Traps That Destroy Freelance Savings
Building a safety net is only half the battle. Protecting that money from your own bad decisions is where the real challenge begins. People with unpredictable incomes often fall into psychological traps that drain their bank accounts completely empty.
You can work incredibly hard for months to build a solid financial buffer, only to ruin it in one single weekend. This usually happens because we lie to ourselves about what we can actually afford. Let us break down the most dangerous mistakes you need to avoid at all costs.
The Danger of Blurred Financial Lines
The absolute quickest way to destroy your personal emergency fund is by using it to fund your business. Many gig workers treat their personal savings like a readily available business loan. They dip into their safety net to buy new software, upgrade their camera, or run advertising campaigns.
This is a massive mistake that leaves you incredibly vulnerable. Your personal survival money should never be used to solve business problems. If you have a sudden technical emergency and need to fix your slow internet connection to meet a deadline, that money should come from your business revenue, not your personal savings.
When you start mixing these two worlds, you lose total track of your actual financial health. A recent Federal Reserve report on gig worker financial stability shows that co-mingling funds is the number one reason freelancers go bankrupt. You must maintain an aggressive, permanent wall between your business expenses and your personal safety net.
Falling for the "Next Month" Promise
Have you ever looked at a shiny new purchase and told yourself, "I will just buy this now and save double next month"? This is the most common lie variable income earners tell themselves. You are basically borrowing money from a future that is completely unwritten.
When next month arrives, a client might delay a payment, or your car might break down. Suddenly, you cannot make that double savings deposit you promised yourself. You are now stuck with expensive new stuff and a shrinking bank account.
You can never predict what your income will look like thirty days from now. Therefore, you must only make financial decisions based on the actual cash sitting in your account today.
Letting Lifestyle Creep Steal Your Security
When you finally string together three or four highly profitable months, you start to feel completely invincible. You stop looking at the price tags at the grocery store. You start upgrading your daily coffee habit and taking extra weekend trips.
This subtle increase in spending is called lifestyle creep, and it is a silent wealth killer. Before you know it, your baseline survival number has magically doubled.
Now, your carefully built emergency fund only covers half the time it used to cover. You can still upgrade your life, but you should find creative ways to do it without spending a fortune. For example, instead of renting an expensive external office, you can make your tiny room look huge by simply maximizing natural light and rearranging your current desk setup.
Always keep your basic living costs as low as possible. The lower your monthly baseline remains, the longer your money will protect you during a massive drought.
Your Blueprint for Complete Financial Peace
Taking control of your money when your paycheck constantly changes is incredibly empowering. You are no longer acting like a passive passenger on a terrifying financial rollercoaster. You are now the driver, carefully steering your way around the bumps in the road.
By calculating your absolute bare-bones survival number, you know exactly what you need to survive. By creating physical distance with a separate holding account, you protect your cash from emotional spending.
Most importantly, you are building a wall of security that gives you the ultimate freedom to live on your own terms. You can finally start managing your overall lifestyle without the constant, heavy burden of financial panic weighing you down.
A 48-Hour Action Plan to Get Started
You do not need to fix your entire financial life today. You just need to take a few small, highly intentional steps to get the momentum going. Here is exactly what you should do over the next forty-eight hours.
First, sit down with a blank piece of paper and write out your absolute survival number. Be brutally honest with yourself about what is actually essential.
Second, go online and open a brand new, fee-free holding account at a completely different bank. Do not request a debit card for this new account.
Finally, set up an automatic transfer to move ten percent of your very next payment directly into this new account. It does not matter if that next payment is fifty dollars or five thousand dollars. Just force the system to start working for you.
I spent years losing completely sleepless nights, staring at my ceiling and wondering how I would pay my rent. The exact day I finally separated my accounts and strictly defined my survival number, that heavy anxiety permanently vanished from my life. You have the exact same power to take back your peace of mind starting right now.
Answers to Your Biggest Unpredictable Income Worries
How much money should a freelancer realistically keep in an emergency fund?
If you have a highly unpredictable income, you should aim for a minimum of six months of your bare-bones survival expenses. Because freelance work can suddenly dry up without any warning, a standard three-month fund is usually too risky. This larger buffer gives you plenty of time to find new clients without panicking.
Where is the safest place to store my irregular income savings?
You should store this money in a high-yield savings account that is completely separate from your daily checking account. This keeps the money easily accessible if a real disaster strikes, but slightly out of reach so you do not spend it on impulse purchases. Make sure the bank you choose offers strong interest rates to fight off inflation.
Should I focus on paying off my credit card debt or building my safety net first?
You must build a one-month survival buffer before you start aggressively attacking your credit card debt. If you throw all your spare cash at debt and your income suddenly drops to zero next week, you will just have to use the credit cards again to buy groceries. Having a small cash buffer actually breaks the cycle of endless debt.
What exactly should I do if I have a month where I make zero dollars?
Do not panic, because this is exactly what your holding account is designed to handle. You will simply transfer your normal survival number from your holding account buffer to your checking account. You will continue to live your normal, minimal lifestyle while spending your newly available free time aggressively pitching new clients.
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be construed as professional financial advice. Always consult with a certified financial planner or financial advisor before making any major decisions regarding your personal savings, taxes, or business finances.