The Illusion of the Big Paycheck: My Personal Wake-Up Call
I still remember the exact day I got my biggest career promotion. I was absolutely thrilled because I finally hit a salary number I had only dreamed about. I immediately thought my money worries were gone forever. But exactly six months later, I looked at my bank account and felt a cold rush of panic.
I was making more money than ever before, yet I had less cash in my savings account. I felt like a complete failure because I could not understand where all those extra dollars were going. Every time my paycheck hit, it seemed to vanish into a black hole of new bills, nicer dinners, and upgraded subscriptions. I was earning a top-tier income, but I was still silently living paycheck to paycheck.
This is a quiet struggle that so many professionals face every single day. You work incredibly hard, secure a fantastic job, and bring home a heavy paycheck. Friends and family think you have it all figured out, but behind closed doors, the anxiety is eating you alive.
The mental weight of appearing wealthy while actually being broke is exhausting. You lose sleep wondering how you will handle a sudden medical bill or an unexpected home repair. The fear of losing your job becomes terrifying because your expensive lifestyle completely depends on that next payday.
It feels like running on a treadmill that keeps speeding up. No matter how fast you run or how much you earn, you never actually move forward. This constant financial pressure destroys your peace of mind and puts a massive strain on your personal relationships. We are taught that earning more money solves everything, but reality paints a very different picture.
Why We Fall for the Money Myth: A Quick Reality Check
Before we fix the problem, we need to understand why this happens. Society has trained us to confuse how much money we make with how much money we actually have. We see a neighbor with a brand-new luxury SUV and immediately assume they are financially secure.
The truth is, that SUV might be fully financed with a terrible interest rate. High earners are heavily targeted by banks for massive credit limits and premium loans. It becomes dangerously easy to borrow money based on your future income.
This creates a dangerous illusion of wealth. You are surrounded by nice things, but you do not actually own them; the bank does. True financial peace does not come from the items you display to the world. It comes from the quiet comfort of having cash in the bank and investments growing in the background.
Myth vs. Reality in Personal Finance:
- The Myth: Making a six-figure salary makes you rich.
- The Reality: Keeping and investing a portion of your salary is what makes you rich.
- The Myth: Upgrading your lifestyle is a normal reward for working hard.
- The Reality: Blindly upgrading your lifestyle without saving first is a fast track to financial anxiety.
Breaking the Cycle: The Blueprint for True Financial Peace
If you are tired of making good money but having nothing to show for it, it is time for a massive shift in how you handle your finances. You do not need to feel guilty, but you do need a new system. Let us walk through some practical, science-backed steps you can apply starting today to protect your high income.
Step 1: Plugging the Leaky Bucket of Lifestyle Creep
Lifestyle creep is the silent thief that steals your future wealth. When your income goes up, your hidden expenses magically rise to meet it. You start buying premium groceries, upgrading your car, and taking more expensive vacations.
None of these things are inherently bad on their own. The problem starts when these upgrades happen automatically without any intentional planning. Your brain quickly adapts to these new luxuries, and soon they just feel like normal necessities.
To stop this, you need to forcefully create a gap between what you earn and what you spend. Every time you get a raise, pretend it never happened. Take at least 50% of that new money and automatically route it directly into an investment or savings account.
Step 2: Escaping the Premium Debt Trap
High-income earners often carry the most dangerous types of debt. Because banks see your high salary, they easily approve you for massive mortgages and shiny rewards credit cards. You might think you can easily handle the monthly payments.
But high monthly payments lock you into a financial prison. If your income drops or you want to change careers, those heavy debt obligations become a nightmare. You are essentially renting your current lifestyle using your future time and energy.
You need to attack this debt with intense focus. Start by completely paying off any consumer debt, especially credit cards and personal loans. True financial freedom means owing nothing to anyone. When your paycheck is finally yours to keep, your entire perspective on work and life will change.
Step 3: Redefining What an Emergency Fund Means for You
Most basic financial advice tells you to save three months of expenses for emergencies. But when you have a high income and a high-cost lifestyle, three months is simply not enough. High-paying jobs often take much longer to replace if you get laid off.
You need a fortress of safety around your life. I highly recommend building an emergency fund that covers six to nine months of your basic living costs. This money should not be invested in risky stocks; it needs to sit in a high-yield savings account where you can grab it instantly.
Pro Tip: I used to think keeping a large amount of cash in savings was a waste of potential investment growth. But my realization came when my company went through sudden layoffs; having that cash cushion completely eliminated my anxiety and allowed me to think clearly. Treat your emergency fund as an insurance policy for your mental health, not as a tool to get rich.
The Psychology of "I Deserve It" Spending
Working a demanding, high-stress job takes a massive toll on your emotional energy. After a brutal 60-hour work week, your brain actively looks for a dopamine hit to feel better. This is exactly when the "I deserve it" spending happens.
You book a weekend at an expensive resort or buy a designer watch because you feel you earned a reward for your suffering. The problem is that this emotional spending only provides a temporary high. A week later, the excitement fades, but the credit card bill remains.
You have to break this emotional link between stress and spending. Find completely free or low-cost ways to decompress after a tough week. Go for a long hike, read a fantastic book, or just disconnect your phone. Reward yourself with actual peace and quiet instead of buying more clutter.
A Quick Look at Financial Health:
Step 4: Shifting Your Mindset from Earner to Owner
Having a great salary makes you a fantastic earner. But earning alone will never guarantee your long-term stability. You have to transition your identity from just being an earner to becoming an owner.
Owners buy assets that put money back into their pockets. Earners buy liabilities that constantly drain their bank accounts. A luxury boat is a liability because it requires storage fees, maintenance, and insurance. A solid index fund or a rental property is an asset because it generates cash flow.
Start looking at your money as a fleet of tiny workers. Every dollar you invest goes out into the world to earn more dollars for you. If you spend that dollar on a fancy dinner, you have effectively fired that worker forever. Build your army of assets until the income they produce covers your living expenses.
See This Real-Life Strategy in Action:
If you want to understand exactly how to build this wealth system visually, take a look at this brilliant breakdown. Watch the video below to see exactly how smart earners protect their money from vanishing into thin air.
Step 5: Automating Your Financial Success
Human willpower is incredibly limited. If you rely on your own discipline to manually transfer money into savings every month, you will eventually fail. Life gets busy, unexpected bills pop up, and you easily convince yourself to skip saving for just one month.
The most successful wealth builders remove themselves from the process completely. They set up strict automation so their money moves exactly where it needs to go on payday. Before they even wake up on Friday morning, a portion of their check has already gone to investments.
Set up automatic transfers with your bank right now. Direct 20% of your income into an investment account and 10% into a dedicated savings bucket. You will be forced to live entirely on the remaining 70%, which naturally controls your lifestyle creep without you having to overthink every purchase.
Dealing with the Social Pressure of Success
One of the hardest parts of making good money is the silent expectation from society. Your friends want to go to expensive restaurants, and your family expects lavish holiday gifts. People assume that because you have a great title at work, you have bottomless pockets.
Saying "no" when you have a high income feels incredibly awkward. You might fear that people will think you are cheap or struggling financially. But you have to protect your own future aggressively.
Learn to decline expensive invitations politely but firmly. You do not owe anyone an explanation of your financial goals. Suggest alternative, affordable plans like hosting a dinner party at your home instead of dropping hundreds of dollars at a trendy restaurant. True friends will care about spending time with you, not how much money you spend on them.
Recognizing the Difference Between Rich and Wealthy
We often use the words "rich" and "wealthy" interchangeably, but they mean completely different things. Being rich simply means you have a high current income. A highly paid lawyer who spends everything they make is rich, but they are incredibly fragile.
Being wealthy means having unspent money, hidden assets, and absolute freedom over your time. Wealth is the luxury cars you chose not to buy and the expensive clothes you left on the rack. It is the invisible safety net that lets you sleep perfectly at night.
Your goal should never be just to look rich to strangers on the internet. Your primary goal must be to build invisible wealth that gives you total control over your life. When you truly understand this difference, saving money stops feeling like a punishment and starts feeling like a superpower.
Step 6: Conducting a Ruthless Monthly Audit
You cannot fix what you do not measure. A high salary often makes people lazy about tracking their expenses because there is usually enough money to cover the basics. But small, unnoticed leaks will eventually sink a massive ship.
Pick one day every month to sit down and review every single transaction on your accounts. You will be shocked at how many forgotten subscriptions or random daily expenses are draining your funds. I call this the monthly reality check.
Focus on these key areas during your audit:
- Recurring Subscriptions: Cancel anything you have not used in the last 30 days.
- Food Delivery Apps: Total up exactly how much you spent on delivery fees and tips. The final number will probably horrify you.
- Convenience Spending: Notice how often you pay a premium just because you were too tired or disorganized to plan ahead.
When you bring awareness to these small leaks, you instantly regain control. You stop wondering where your money went and start telling it exactly where to go.
Why Your Future Self Will Thank You
Every financial decision you make today is a direct gift or a massive burden to your future self. When you choose to invest your money instead of upgrading your lifestyle, you are buying future freedom. You are buying the option to retire early, start your own business, or take a year off to travel.
A high income is an incredible blessing, but only if you use it correctly. It is a powerful tool, not a permanent guarantee of safety. If you respect your money and give it a clear purpose, it will take care of you for the rest of your life.
Take the steps we discussed and start small. You do not have to fix everything overnight. Pick one thing, like automating your savings or canceling useless subscriptions, and do it today.
Reclaiming Your Peace of Mind
Financial stability is not about reaching a specific magical number in your bank account. It is a deep feeling of security and control. It is knowing that no matter what happens in the economy or at your job, you and your family are going to be perfectly fine.
Stop letting your high salary trick you into a false sense of security. Start building the strong financial foundation you actually deserve. The moment you take back control of your money, the heavy anxiety will start to lift.
You have worked entirely too hard to get where you are today. Do not let poor money management steal the rewards of your success. Take action, build your assets, and turn your fantastic income into lifelong, unbreakable financial stability.
Next-Level Wealth Building Tactics for Top Earners
Now that we have covered the basic foundations of protecting your money, it is time to look at the bigger picture. Moving from simply paying bills to actively building a massive safety net requires a shift in strategy. You need systems that run quietly in the background of your life.
One of the smartest things you can do is implement a reverse budgeting system. Instead of tracking every single coffee purchase, you focus entirely on your savings target first. You take your massive income and immediately strip away the money meant for investments and emergency funds.
Once those wealth-building buckets are full, you have complete permission to spend whatever is left without an ounce of guilt. This completely removes the daily stress of tracking pennies. You know your future is secure, so your present spending becomes completely stress-free.
You also need to think about diversifying your human capital. When you have a high-paying job, your entire financial world usually relies on a single company. If that company faces a massive downturn, your primary source of cash disappears overnight.
Start building alternative streams of income that have nothing to do with your main career. This could be dividend investing, renting out property, or even a small side business. If you are interested in creating something meaningful outside of your day job, you might want to learn about understanding what people truly value to start a successful side project.
The Psychology of "Invisible Wealth"
Most people struggle with the concept of invisible wealth because human beings are highly visual creatures. We want to see the results of our hard work in the form of nice cars, big houses, and expensive clothes. But real financial stability is incredibly boring to look at.
Real wealth is hidden away in retirement accounts, index funds, and equity in your home. You have to train your brain to get excited about these invisible numbers growing on a screen. Every time you see your investment account hit a new milestone, give yourself a mental high-five.
Understanding the psychological connection between money and stress is incredibly helpful. The American Psychological Association regularly studies financial anxiety, showing that even top earners suffer when their visible spending outpaces their invisible savings. You have to actively fight the urge to display your wealth to strangers.
Escaping the Golden Handcuffs
Have you ever heard the term "golden handcuffs"? It happens when a company pays you so much money that you feel trapped in a job you absolutely hate. You cannot leave because your expensive lifestyle completely relies on that massive monthly check.
Breaking free from these handcuffs requires ruthless honesty about what actually makes you happy. Do you really need the massive house in the expensive zip code? Sometimes, optimizing your living space and living a slightly smaller, simpler life brings way more joy than paying a massive mortgage.
When you artificially lower your living expenses, you give yourself the ultimate gift: career flexibility. You can take a lower-paying job that you actually love, or you can take a bold risk and start your own company. Financial independence is simply the freedom to design your own days.
Automating the "Debt Snowball" Strategy
If you currently have multiple high-interest loans, you need a mathematical attack plan. High earners often pay a little bit extra on all their debts, thinking they are making good progress. This scattered approach actually slows down your momentum.
You should target your smallest debt first while paying the minimum on everything else. Once that small debt is gone, you take all that freed-up money and throw it at the next largest debt. The Consumer Financial Protection Bureau offers excellent guidelines on managing debt that perfectly align with this snowball method.
This works brilliantly because it gives your brain quick wins. Paying off that first small credit card releases a rush of dopamine that motivates you to keep going. It is much like fixing frustrating internet issues in your home office; once you remove the annoying friction, everything else runs so much smoother.
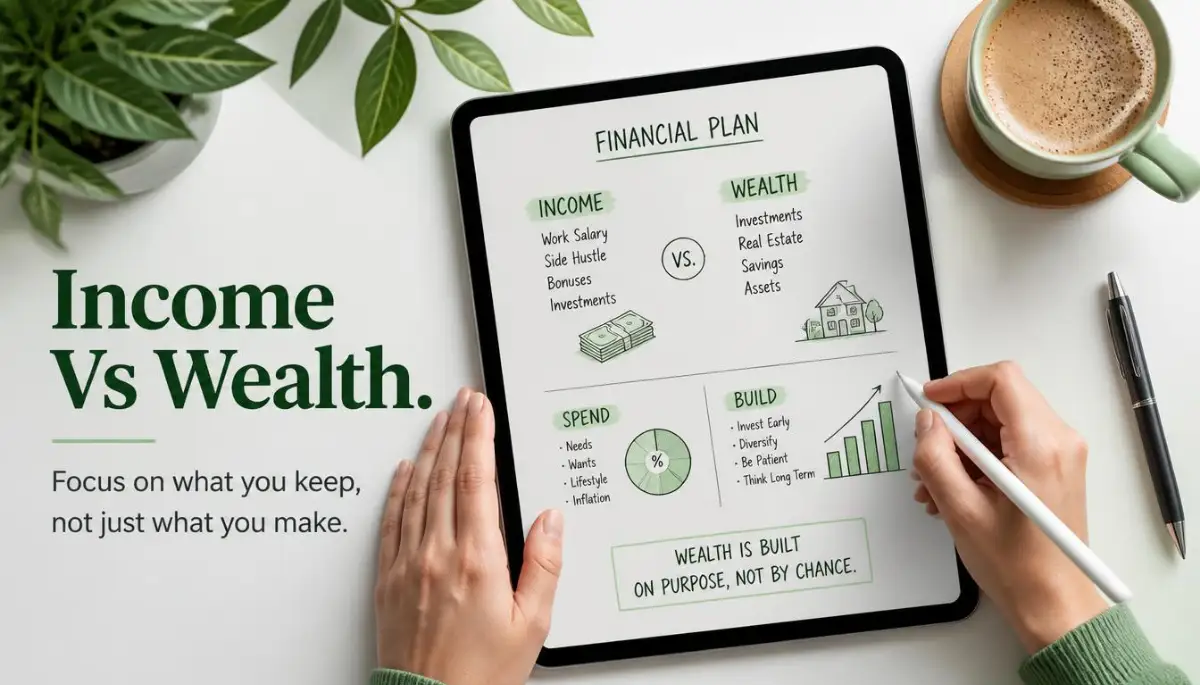
The Silent Wealth Destroyers You Must Avoid
The path to building a secure future is full of dangerous traps, especially for people who make a lot of money. The biggest threat is not a sudden stock market crash; it is the slow, quiet erosion of your cash through bad habits. We need to expose these silent destroyers so you can aggressively guard your paycheck.
Let us look at some of the most common pitfalls that catch smart, high-earning professionals off guard. If you do not recognize these traps early, they will completely consume your financial freedom.
Trap 1: The "New Zip Code" Disaster
This is a classic mistake that happens almost instantly after a big promotion. You decide that your current neighborhood is no longer good enough for your new income bracket. You move to an exclusive zip code, thinking you have finally made it.
But a more expensive house is just the beginning of the trap. Suddenly, you feel pressure to buy furniture that matches the grand house. You feel forced to upgrade your car because your old reliable sedan looks out of place in your new driveway.
This snowball effect is terrifying. The National Bureau of Economic Research has published fascinating data showing how peer pressure and neighbor comparisons directly drive up personal debt. Before you know it, your massive salary is completely eaten up by the cost of simply blending in with your new neighbors.
Trap 2: Believing Future Income is Guaranteed
When you are young and earning a lot, you naturally assume your income will only go up. You make massive financial commitments based on the idea that next year's bonus will cover the gap. This is incredibly dangerous thinking.
Industries change, companies restructure, and personal health issues can suddenly halt your earning power. If your entire life is built on the assumption of endless future promotions, a single bump in the road will crash your reality.
Never finance a lifestyle based on a bonus you have not received yet. Base your daily living expenses strictly on your guaranteed base salary. Treat any bonuses, commissions, or extra income as magical windfalls that go straight into your wealth-building accounts.
Trap 3: Ignoring the "Small Leaks"
When you make a lot of money, a $50 dinner or a $100 subscription feels like absolute pocket change. You stop looking at price tags and you completely ignore your bank statements. You tell yourself that you work too hard to worry about small numbers.
But math does not care about your feelings. A hundred tiny leaks will sink a massive ship just as fast as one giant hole. Fifty dollars a day in random convenience spending adds up to over $18,000 a year.
That is $18,000 that could have been invested in the stock market, gathering compound interest for your early retirement. You do not have to become painfully cheap, but you absolutely must stay aware of where your money is flowing.
Trap 4: Mixing Net Spend with Self-Worth
This is the deepest emotional mistake high earners make. You start to believe that your value as a human being is tied directly to the brands you wear or the restaurants you visit. You feel a constant, exhausting need to prove your success to everyone around you.
When you tie your self-worth to your spending, cutting back feels like a personal failure. You become terrified of anyone thinking you are struggling. This pride keeps you locked in a cycle of endless consumerism.
You have to completely separate your bank balance from your personal identity. The most successful people in the world often wear plain clothes and drive ordinary cars because they simply do not care about impressing strangers. Their confidence comes from their massive, hidden financial security.
Your Action Plan for Lasting Financial Peace
We have covered a massive amount of ground today, and I know this can feel slightly overwhelming. But you do not need to fix your entire financial life by tomorrow morning. Real, lasting change happens through tiny, consistent actions over a long period of time.
You already have the hardest part figured out: you have a powerful income engine. Now, you just need to steer that engine in the right direction. Let us build a quick, practical checklist you can start working on this exact week.
The 48-Hour Cash Flow Challenge
Action 1: Open your banking app right now and look at your last 30 days of transactions. Highlight every single purchase that was driven by stress, convenience, or trying to impress someone else.
Action 2: Log into your payroll system at work. Increase your automatic retirement contribution by just 2%. You will barely notice the difference in your paycheck, but your future self will be incredibly grateful.
Action 3: Have an honest conversation with your spouse or partner about your new goals. You must operate as a unified team if you want to break the cycle of living paycheck to paycheck.
Redefining Your Relationship with Money
Money is not a trophy meant to sit on a shelf and gather dust. It is simply a tool that you use to carve out the life you actually want to live. Stop giving your power away to luxury brands and expensive banks.
Every time you choose to save instead of spend, you are buying a tiny piece of your future freedom. You are buying the ability to say "no" to a bad boss. You are buying the peace of mind that lets you sleep deeply through the night.
If you want to keep expanding your knowledge and taking control of your life, I highly recommend exploring different strategies for personal growth. Building wealth is a lifelong journey, and educating yourself is the best investment you will ever make.
I know exactly how exhausting it feels to work incredibly hard and still feel financially vulnerable, because I lived that exact nightmare. But the moment my mindset shifted from "looking rich" to "building real wealth," my entire life changed for the better. You absolutely have the power to protect your income and create a life of total financial peace starting today.
Honest Answers to Common Money Questions
Does a high salary automatically mean a good credit score?
Not at all. Your credit score is based on how reliably you pay your debts, not how much money you make. A person making a modest income who pays their bills on time can easily have a much higher score than a high earner who maxes out their credit cards.
How much of my high income should I actually save?
If you want to build true stability, saving just 10% is rarely enough for high earners. You should aggressively aim to save and invest at least 20% to 30% of your take-home pay. The more you can save without feeling completely miserable, the faster you buy your freedom.
Is it too late to start saving if I already upgraded my lifestyle?
It is never too late to take back control of your money. You might have to make some uncomfortable choices, like downsizing a car or canceling expensive memberships. But a few months of awkward adjustments is vastly better than a lifetime of financial anxiety.
Why do I feel completely broke even though I make six figures?
You are likely a victim of rapid lifestyle creep. When your expenses constantly rise to meet your new income, you never actually create a buffer of cash. You feel broke because your money leaves your account just as fast as it comes in.
Can I still enjoy my money while building wealth?
Absolutely! Building wealth is about intentional spending, not total deprivation. You can happily spend money on the things that truly bring you joy, as long as you ruthlessly cut costs on the things that do not matter.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial, investment, or legal advice. Every individual's financial situation is unique. Please consult with a certified financial planner or professional advisor before making any major financial decisions.